Solar Power Outruns the Tariff Wars
Despite heavy tariffs and shifting tax rules, utility-scale solar is breaking records and proving its economics can survive any political climate.
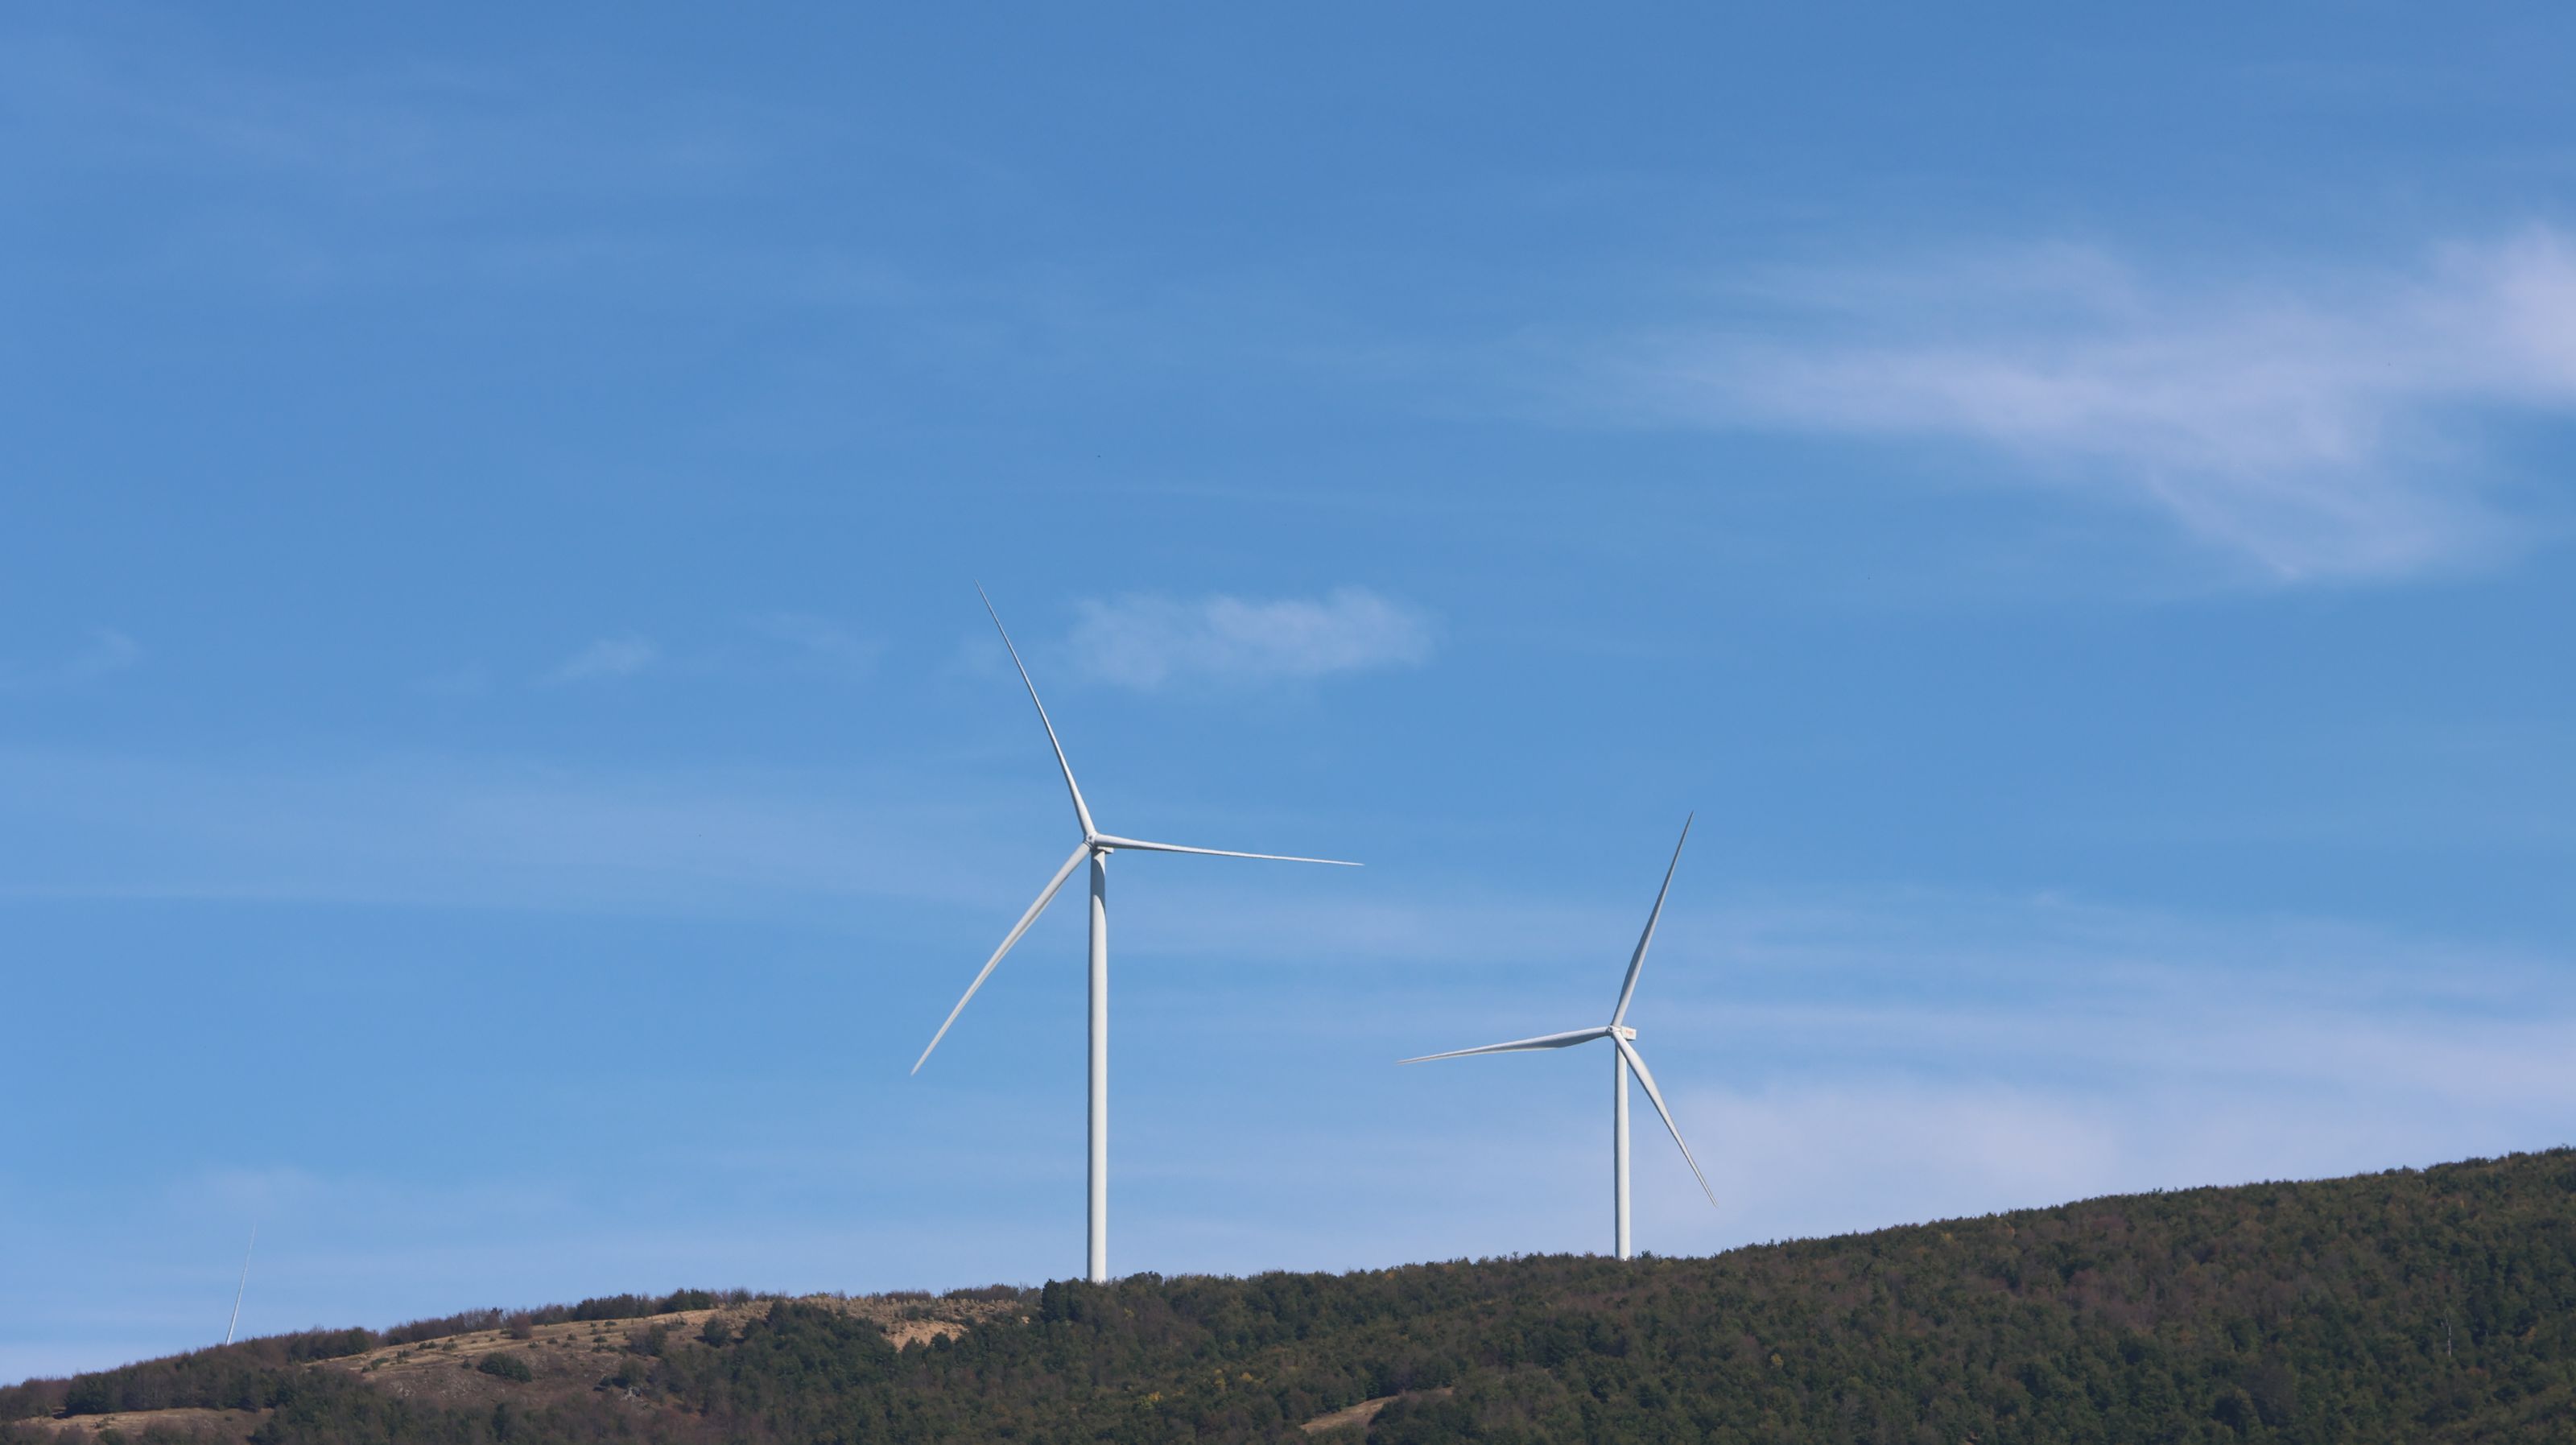
The United States is on track to add a staggering 42,971 megawatts of utility-scale solar capacity this year, defying a barrage of trade barriers and tax policy shifts. For years, critics argued that the transition to clean energy was a fragile construct held up entirely by government subsidies and favorable trade terms. Instead, solar deployment is breaking records even as federal sourcing rules tighten and tariffs on Asian modules intensify. The underlying economics of solar have crossed a critical threshold where market demand simply overpowers regulatory friction.
This resilience comes at a pivotal moment as electricity demand spikes across the country, driven by AI data centers and domestic manufacturing. While natural gas power generation remains flat at roughly 40 percent of the market, renewables are capturing almost all new electricity demand growth. Developers are discovering that utility-scale projects are increasingly straightforward to build compared to complex fossil fuel plants. The market is no longer waiting for a perfect regulatory environment to build out the grid.
The numbers reveal why the sector is moving so fast despite protectionist trade policies. According to recent market reports, solar module prices have plunged by more than 20 percent annually, offsetting rising commercial system costs and stricter labor rules. In Texas, which leads the nation in new capacity, developers have successfully navigated Section 201 tariffs and local grid challenges to deliver gigawatts of cheap power. Even with new domestic sourcing requirements taking effect, the drop in international hardware costs keeps project economics highly attractive.
For climate tech founders and venture investors, this shift redefines the risk profile of clean energy infrastructure. Solar is no longer a policy-dependent play vulnerable to the whims of changing administrations. It has matured into a highly resilient, predictable asset class that behaves more like software in its cost deflation. Startups that focus on project deployment software, grid integration, and supply chain automation are finding a massive, highly motivated customer base ready to scale.
Over the next twelve months, expect this momentum to accelerate as developers adapt to the new sourcing baseline. Companies will increasingly lock in domestic supply chains to secure maximum tax credits, driving a localized manufacturing boom. This transition will temporarily squeeze mid-market developers, but the sheer volume of incoming utility-scale capacity will easily offset these localized bottlenecks. By this time next year, solar will not just be competing with fossil fuels on price, it will be actively pricing them out of new grid capacity entirely.
 The Future FrontBe on the cover.Twice a month we put the people shaping what's next on our cover.Apply for the cover