2026: Warehouse Robotics Hits a Wall
Enterprise buyers are done with demo reels. Warehouse robotics vendors without hard uptime data are about to find out what a real procurement cycle feels like.
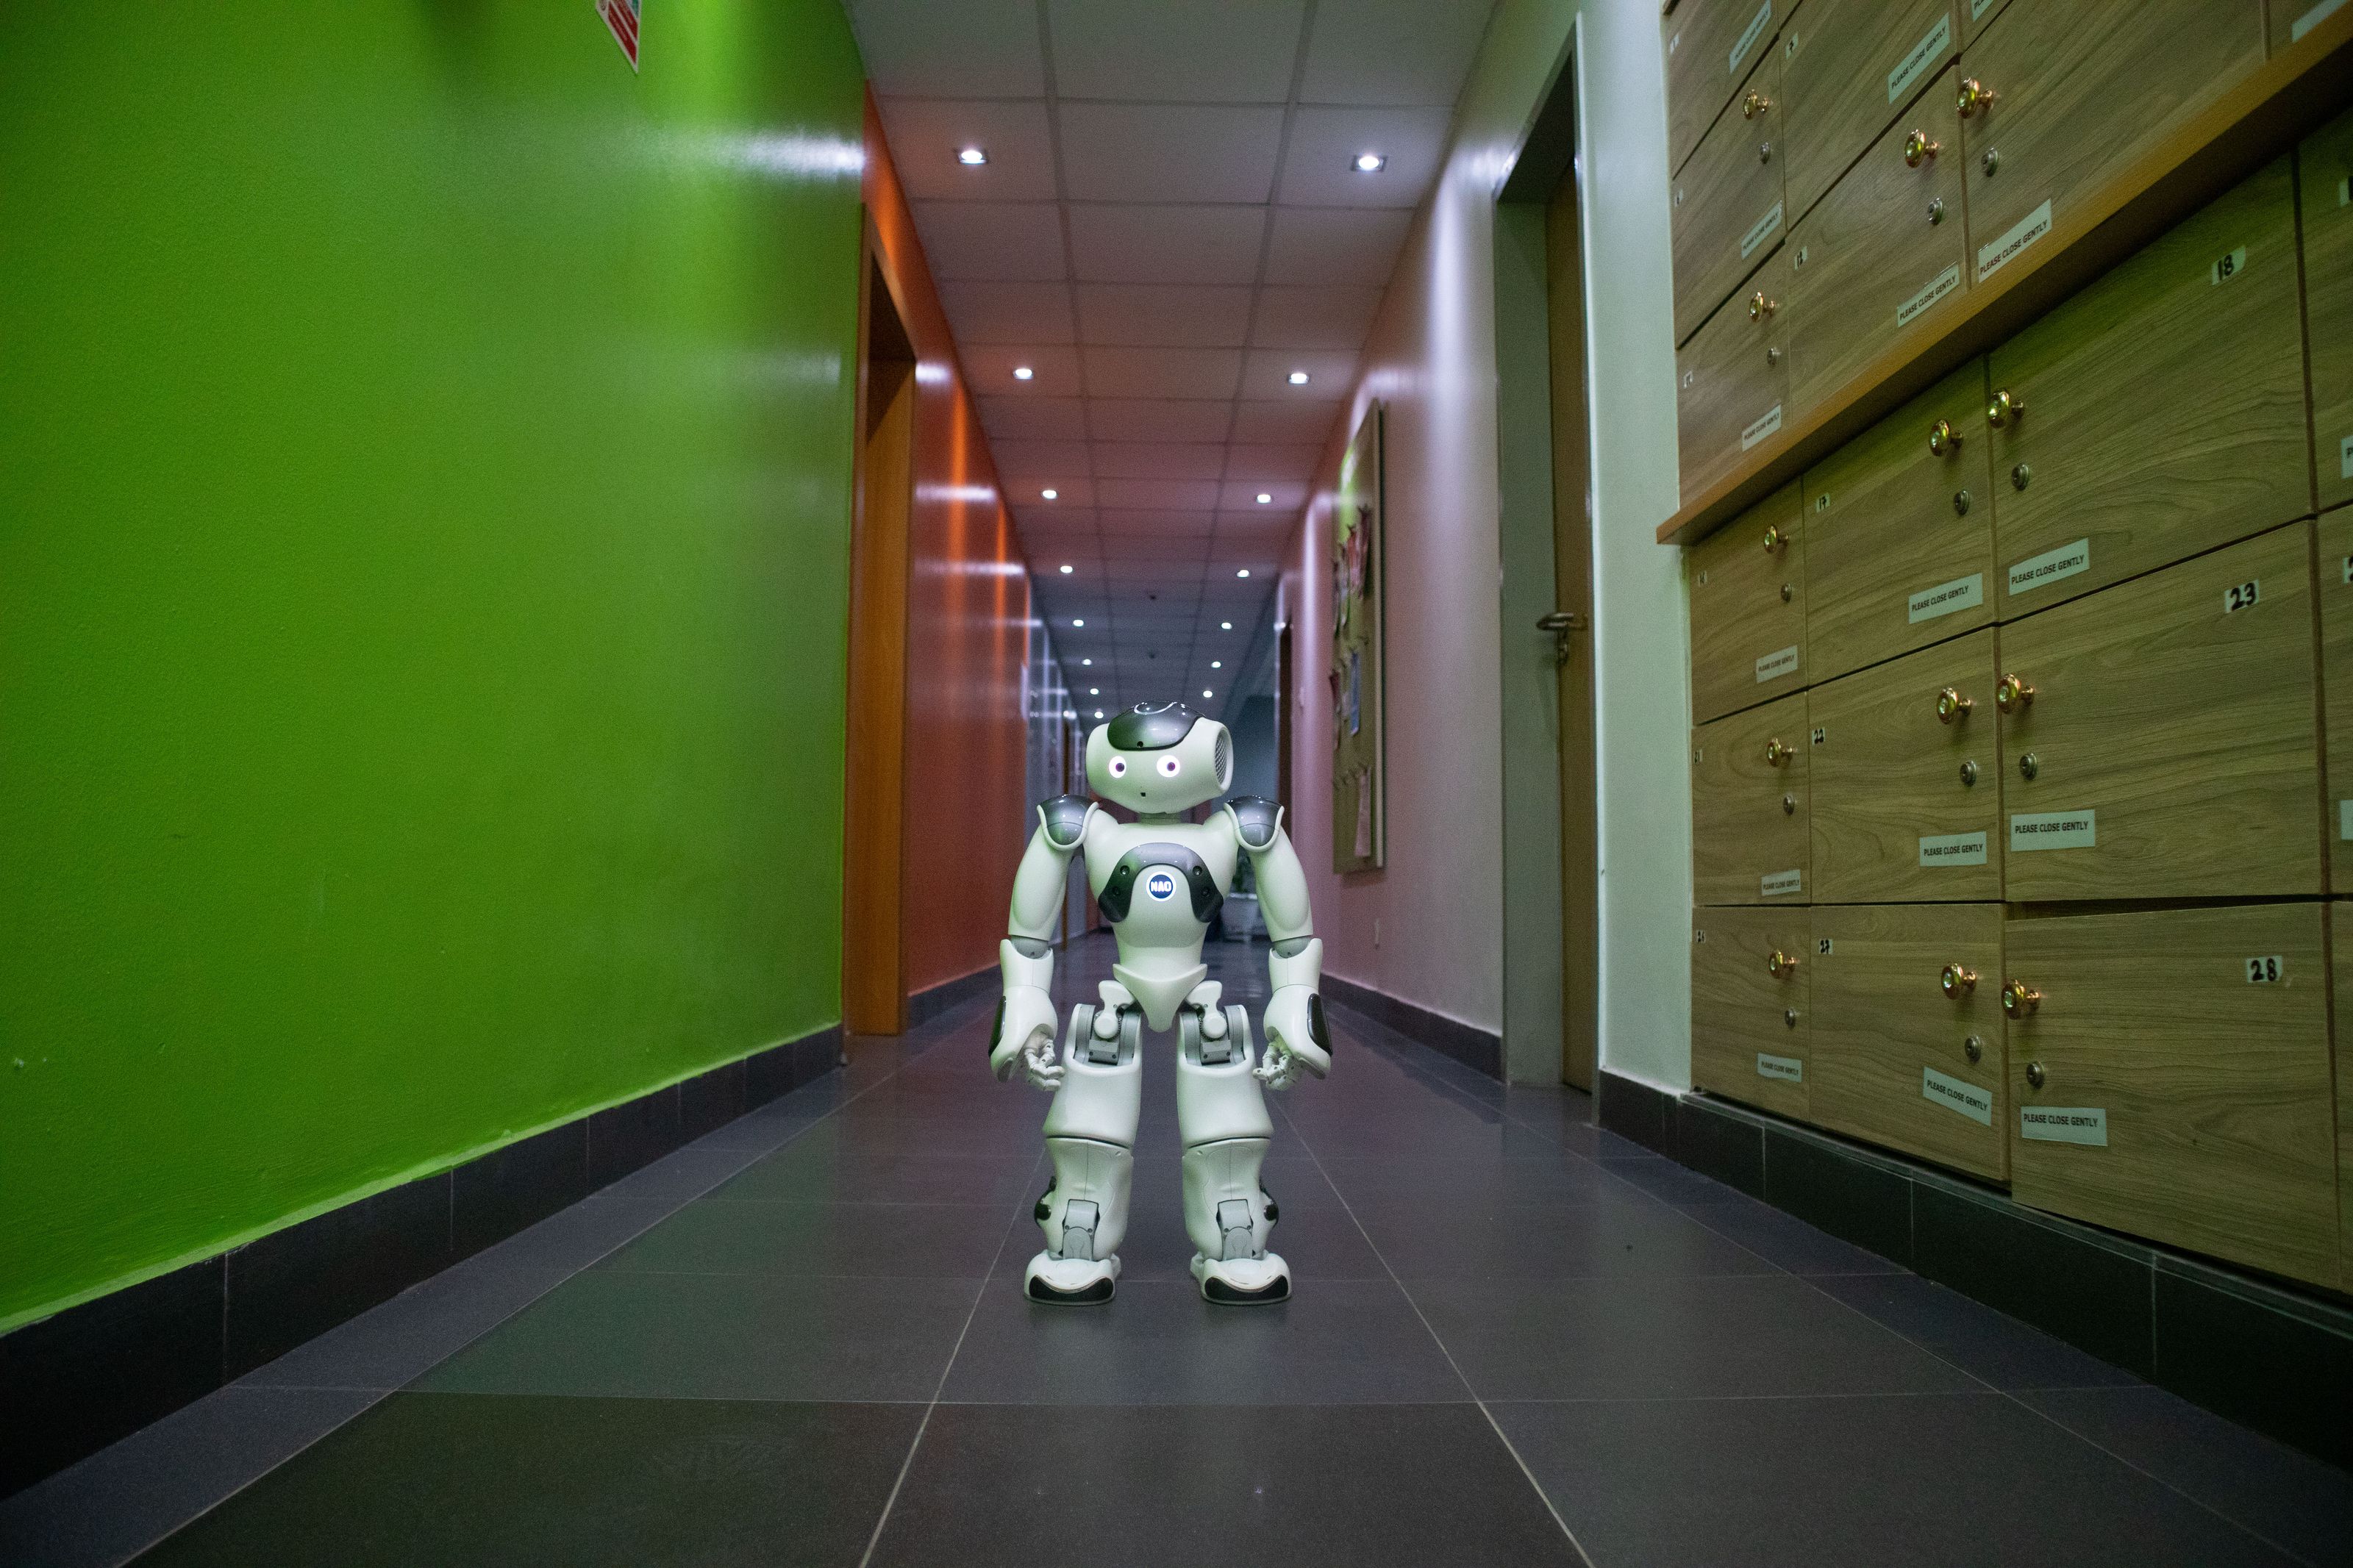
The warehouse robotics market is barreling toward a correction it has long deserved. Enterprise buyers, burned by over-promised throughput and under-delivered uptime, are now demanding independently validated performance data before any contract gets signed. Edited highlight reels and controlled demo environments no longer move procurement committees. In 2026, the ask is simple: prove it works in the real world, at scale, under messy conditions.
The stakes are high enough to justify the scrutiny. Analysts tracking the warehouse robotics market project sustained double-digit growth through 2033, fueled by e-commerce expansion, persistent workforce shortages, and faster fulfillment mandates. That growth is pulling in serious capital and serious buyers simultaneously. The problem is that the cohort of vendors who scaled on hype during the 2021 to 2024 boom now faces a buyer base that has grown significantly more sophisticated. Procurement teams at large logistics operators have lived through failed deployments. They are not repeating the mistake.
Quality professionals are already demanding more from robotics vendors, and the bar is rising fast in 2026. Gone are the days when edited videos and controlled demos were enough to satisfy procurement teams. Warehouses now want validated proof that a robot can handle damaged packaging, inconsistent lighting, and irregular materials, the edge cases that expose the gap between lab performance and warehouse reality. Network infrastructure is under the same pressure. Organizations investing in designed, thoroughly validated warehouse networking avoid the hidden costs and operational disruptions that patchwork deployments routinely produce. Vendors who cannot produce steady-state and edge-case performance benchmarks are simply being filtered out earlier in the sales cycle.
For investors, this market correction reframes due diligence in a concrete way. Robust field performance data and independent validation benchmarks are becoming non-negotiable signals when evaluating early to growth stage robotics companies. A strong feature set no longer justifies a premium valuation if the operator cannot show enterprise-grade uptime across a meaningful number of live deployments. Founders raising in this environment need to treat reliability documentation not as a post-sales obligation but as a core part of their fundraising narrative. The investors writing the largest checks in the space are increasingly asking for it before term sheets are issued.
Over the next twelve months, expect consolidation to accelerate among vendors who built on demo-stage momentum without investing in real-world validation infrastructure. The operators who survive and scale will be those with structured testing protocols, transparent uptime reporting, and the network architecture to support autonomous systems at full deployment density. Buyers will formalize procurement criteria around third-party benchmarks, pulling validation standards closer to what the medical device and automotive sectors already require. For founders and investors still treating reliability as a second-order concern, 2026 will be an expensive lesson in what enterprise procurement actually looks like when the market grows up.
 The Future FrontBe on the cover.Twice a month we put the people shaping what's next on our cover.Apply for the cover