2026 Is the Reckoning Year for Warehouse Robotics
Warehouse robotics is leaving the pilot phase, and vendors who can't prove real-world reliability are about to find out what that costs.
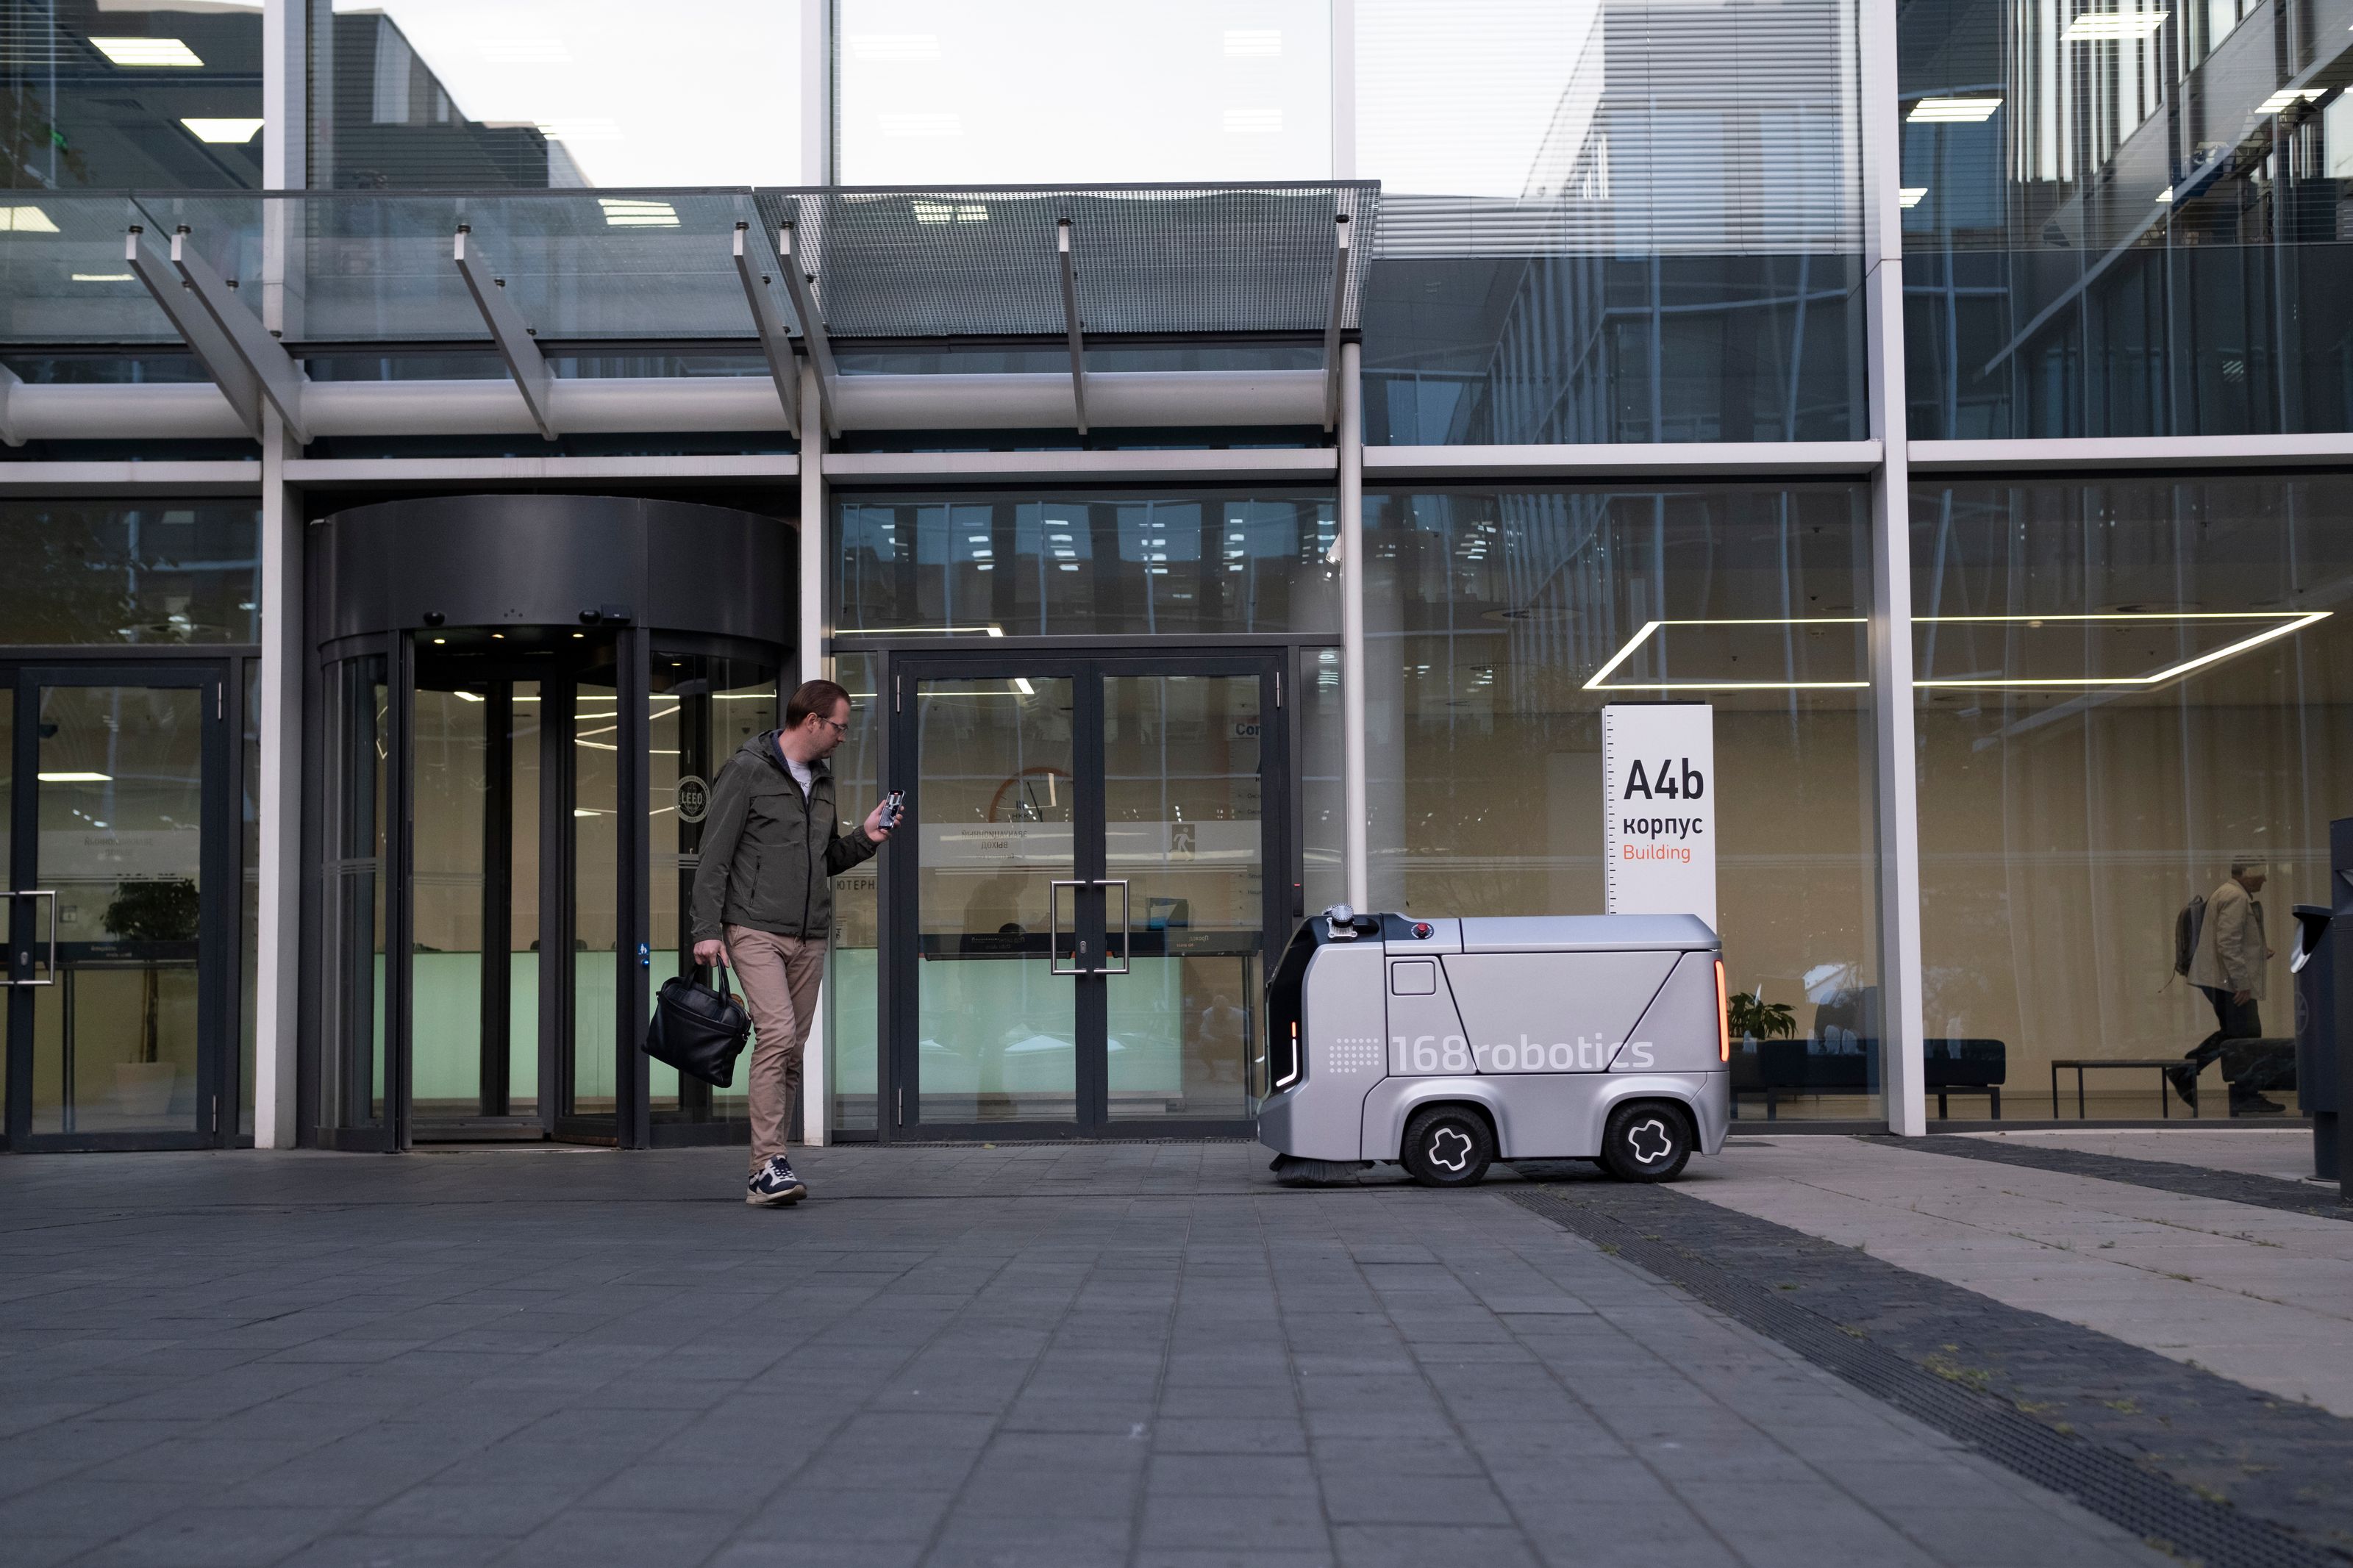
The warehouse robotics market is projected to grow from $7.35 billion in 2026 to $25.41 billion by 2034, a compound annual growth rate of 16.8%. Those numbers look like a rising tide. They are not. Beneath the aggregate growth, a hard sorting is already underway. Buyers have spent two to three years running pilots, accumulating data, and developing procurement instincts they simply did not have before. The vendors who banked on hype-cycle momentum are about to discover that sophistication cuts both ways.
The shift is structural, not cyclical. Enterprise buyers, from third-party logistics firms to large-format retailers, are no longer evaluating robotics on capability demos. They are evaluating on uptime guarantees, maintenance predictability, and auditable quality documentation. This is what market maturation actually looks like: not consolidation for its own sake, but consolidation as a precondition for the kind of standardized, measurable performance that serious operators now demand before signing a multi-year contract.
Vendors that remain narrowly specialized face a compounding problem. A single-application robotics provider cannot offer unified quality documentation across a warehouse workflow, cannot standardize maintenance programs across a mixed-fleet environment, and cannot give a logistics director a single throat to choke when something breaks at 2am. Companies that have moved to unify capabilities, through acquisition or organic expansion, are arriving at this moment with a structural advantage that point solutions simply cannot replicate quickly enough.
For investors, the signal to watch is not revenue growth. It is unit economics tied to deployment reliability. A vendor posting strong bookings numbers while quietly absorbing high maintenance costs, or one whose reference customers are reluctant to speak on the record, is carrying risk that a headline growth rate will not surface. The market's current trajectory, with one estimate placing 2026 value at $10.01 billion and projecting $26.61 billion by 2033, creates enough noise to obscure weak operators for another 12 to 18 months. After that, contract renewal cycles will do the sorting that due diligence should be doing now.
The next 12 months will likely produce the first wave of high-profile contract losses tied explicitly to performance data rather than price. Buyers with two or three years of operational metrics will have the evidence base to make pointed vendor switches, and they will. Founders in this space who have invested in reliability infrastructure, real-time diagnostics, and transparent performance reporting are positioned to absorb that displaced demand. Those who have not will find that the same market growth that once masked their weaknesses is now the benchmark they are being measured against.
 The Future FrontBe on the cover.Twice a month we put the people shaping what's next on our cover.Apply for the cover